Mbanc Connecticut – Non-QM Jumbo Lending for the Nation’s Wealth Corridor
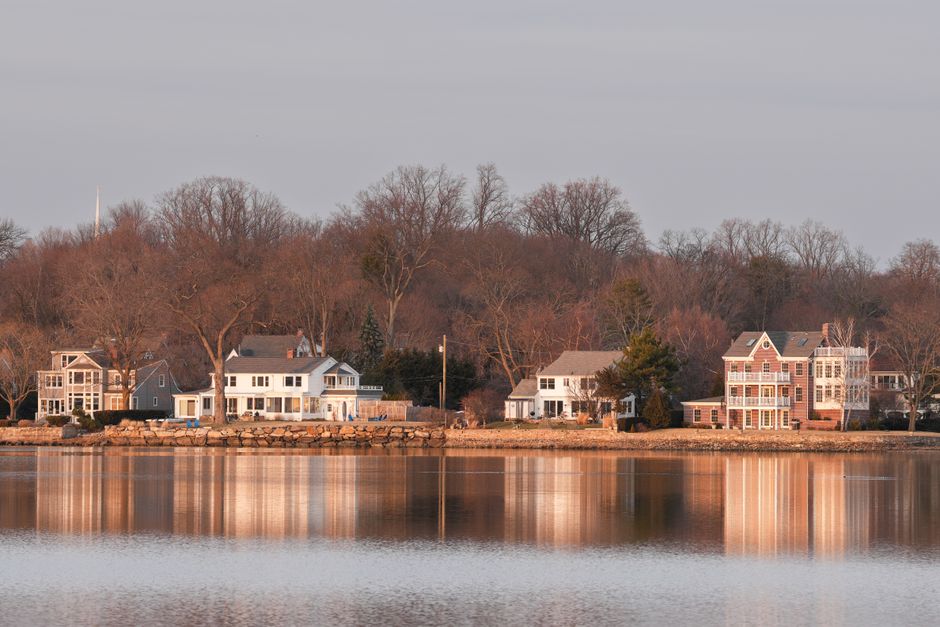
Fairfield County – Greenwich, Stamford, Westport, Darien – concentrates more self-directed wealth per square mile than almost anywhere in America: fund managers, independent advisors, founders and family offices whose income structures rarely fit an agency checklist. Mbanc built its Connecticut practice for exactly these files, and serves the whole state – Hartford, New Haven, the shoreline towns – with primary residence, second home and investment property lending.
Asset utilization is the signature Connecticut program. When your balance sheet is the story – brokerage accounts, retirement assets, liquidity events – Mbanc qualifies you from the asset base itself, no employment income required. It is the natural fit for Greenwich and Westport buyers whose tax returns say little about what they can actually carry.
Bank statement loans serve Connecticut’s independent professionals – consultants, practitioners, agency owners from Stamford to New Haven – qualifying on 12 or 24 months of real deposits instead of post-deduction taxable income.
1099 loans fit Connecticut’s advisor and consultant economy – independent producers in the Hartford insurance corridor and contract specialists across Fairfield County qualify on gross 1099 earnings, with no tax returns in the file.
DSCR rental loans cover Connecticut investors from multifamily in Bridgeport and New Haven to shoreline vacation rentals: the property qualifies on its own cash flow, and your personal income file stays out of it.
Foreign national buyers – a real presence in Fairfield County – can purchase Connecticut property through Mbanc without U.S. credit history, qualifying on the strength of the transaction itself.
Every Connecticut file starts with a sixty-second QuickQual and lands with a Principal Banker who underwrites in-house – the difference between a lender that reads a complex balance sheet and one that routes it to a call center. From Litchfield County weekend properties to Mystic and the shoreline, if the Connecticut asset and the wealth are real, Mbanc can usually structure the loan.
Connecticut occupancy coverage. Connecticut is one of Mbanc’s 22 full-residential states: primary residence, second home and investment property are all available statewide, under every qualification method Mbanc offers.
Connecticut licensing. Licensed by the Connecticut Department of Banking, Mortgage Lender License #ML-38232. NMLS Company Identifier #38232.
Equal Housing Lender. Loans subject to credit approval. Not a commitment to lend. Programs and terms subject to change. Your Principal Banker will confirm the exact figures for your scenario.
View our Connecticut Clear Approval program details.
Connecticut Mortgage and Housing News
Daily coverage of the Connecticut stories that move home prices, property taxes, insurance, and lending, and what each one means for homeowners, buyers, and investors here.
-

Connecticut Flash Flood Risk: Homeowner and Buyer Guide
Connecticut flash flood risk may rise after heavy rain. Learn what homeowners, buyers, and investors should review for damage, insurance, and access.
-
Connecticut Flood Insurance Costs for Homebuyers and Investors
Connecticut flood insurance costs can raise ownership expenses. Learn what buyers, homeowners and investors should review before closing.
-
Connecticut Shoreline Flooding: Guidance for Property Owners
Connecticut shoreline flooding may affect repairs, insurance, and financing. Learn what Connecticut homeowners and buyers should review before acting.
-
Connecticut Mortgage Rates: What the Fed Hike Means
Connecticut mortgage rates may face pressure after the Fed hike. Learn what the September 16 decision means for buyers, owners, and investors.