
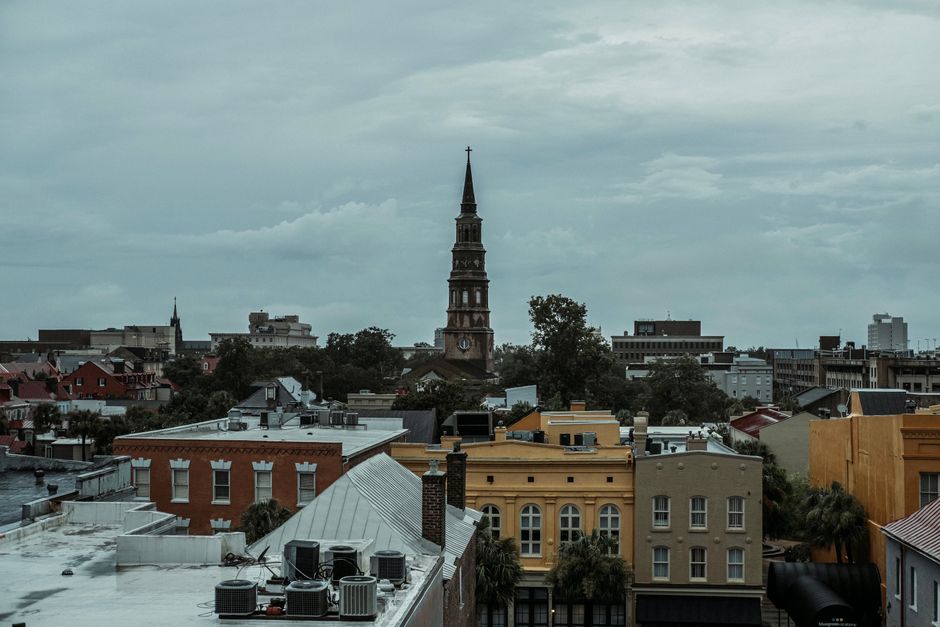
- What happened: The Post and Courier reported on September 25, 2026, that a nor’easter was expected to bring strong winds, coastal flooding, and dangerous rip currents during king tides.
- Who it affects: Charleston coastal homeowners, homebuyers, property investors, and people traveling near affected areas may need to monitor conditions.
- Where: The expected conditions involve the Charleston area and South Carolina coast.
- Source: The Post and Courier, published September 25, 2026
What happened along the Charleston, South Carolina coast?
According to the Post and Courier on September 25, 2026, a nor’easter was expected to affect the Charleston area with strong winds, coastal flooding, and dangerous rip currents. King tides are higher-than-usual tides that can raise the baseline water level along the coast and make flooding more likely in vulnerable locations.
According to the Post and Courier on September 25, 2026, the combination of wind, coastal water, and king tides created safety concerns for the Charleston area. Strong winds and coastal water can affect roads, driveways, utilities, and structures, while rip currents create additional hazards near the beach. Charleston coastal property risk can vary substantially by location, drainage, elevation, and access.
Source: postandcourier.com
Why does Charleston coastal property risk matter to homeowners, buyers, and investors?
How can insurance affect coastal property decisions?
Flood and wind damage may be handled differently under an insurance policy. A standard homeowners policy may not cover every type of flood loss, and coastal properties may have separate requirements, exclusions, deductibles, or coverage limits. Homeowners should review the policy and ask an insurance professional which protections apply to the specific property.
For buyers, insurance availability and cost can affect total housing expenses and whether a property fits the budget. Lenders generally require adequate property insurance, so a buyer may need to resolve coverage questions before closing. Investors should also consider whether a property can be repaired, accessed, and operated if roads or utilities are disrupted.
Charleston coastal property risk can affect both insurance review and purchase timing.
What property conditions should Charleston buyers inspect?
Wind and water can expose maintenance issues that are not obvious during a standard showing. Buyers may want to review roof condition, exterior openings, drainage, crawl spaces, grading, and signs of previous water intrusion. A professional inspection can identify conditions that deserve further review, although no inspection can guarantee that a property will avoid future storm damage.
Flooding can delay inspections, appraisals, repairs, and final walk-throughs if roads are closed or a property cannot be safely reached. Buyers and sellers should communicate promptly with their agents, lender, insurer, and other transaction professionals if conditions interfere with a transaction.
Can coastal conditions affect value and financing?
A single weather event does not automatically determine a property’s value. Repeated flooding concerns, insurance gaps, repair needs, or limited access can influence how buyers evaluate coastal real estate. Investors may need reserves for insurance, maintenance, repairs, and periods when a property cannot be occupied or rented.
Before making an offer, buyers can compare a property’s flood history and elevation information with the cost and availability of insurance. Buyers should also ask whether the intended use, such as a primary residence, second home, or investment property, changes insurance or financing requirements. A lender can explain loan documentation, while property-specific flood and wind questions should go to a qualified insurance professional.
Charleston coastal flooding can create property-access and transaction delays.
What should Charleston property owners watch next?
- Updated weather, coastal flooding, beach, and rip-current warnings for the Charleston area.
- Whether local roads, bridges, utilities, or public access points are affected.
- Property-specific inspection findings, water intrusion, wind damage, or required repairs.
- Insurance confirmation, including flood and wind coverage, before a purchase or refinance moves forward.
How can South Carolina homeowners and investors review financing when conditions change?
When property conditions, income documentation, or timing make a traditional bank’s process difficult, Mortgage Bank of California dba MBANC (NMLS #38232) may help South Carolina homeowners, homebuyers, and real-estate investors evaluate financing based on a broader view of their circumstances. This can include self-employed entrepreneurs, business owners, contractors, retirees, and other borrowers who may not fit conventional guidelines. Learn more about lending in South Carolina, subject to credit approval and property requirements.
Bottom line for Charleston, South Carolina: Charleston coastal property risk can involve flooding, wind, rip currents, insurance questions, and access delays. Homeowners, buyers, and investors should review current warnings and property-specific coverage before making a decision.
More South Carolina coverage
- South Carolina Mortgage Rates: What Above 7% Means (September 25, 2026)
- South Carolina Coastal Insurance: Coverage Options (September 24, 2026)
- South Carolina Housing Market: Okonite Expansion Impact (September 23, 2026)
Go Deeper
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
What is Charleston coastal property risk?
Charleston coastal property risk includes exposure to strong winds, coastal flooding, dangerous rip currents, insurance questions, and access disruptions. The Post and Courier reported these expected conditions for the Charleston area during king tides on September 25, 2026. Risk varies by a property’s location, drainage, elevation, condition, and available coverage.
Should Charleston coastal homeowners review insurance before a nor’easter?
Yes. Charleston coastal homeowners should review flood, wind, deductibles, exclusions, and coverage limits, then ask a qualified insurance professional about gaps affecting the specific property. Insurance terms can differ by policy, and flood loss may be handled differently from other storm-related damage.
Can Charleston flooding affect a home purchase or refinance?
Yes. Charleston flooding can delay access, inspections, repairs, appraisals, or closing, while insurance requirements can affect a property’s total cost and financing process. Buyers and sellers should communicate with transaction professionals when conditions interfere with safe access or required documentation.
What should investors consider for Charleston coastal property?
Charleston coastal property investors should evaluate property-specific flood and wind risk, insurance availability, maintenance needs, access disruptions, repair reserves, and periods when the property cannot be occupied or rented. Investors should also consider whether the intended use changes insurance or financing requirements.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.