
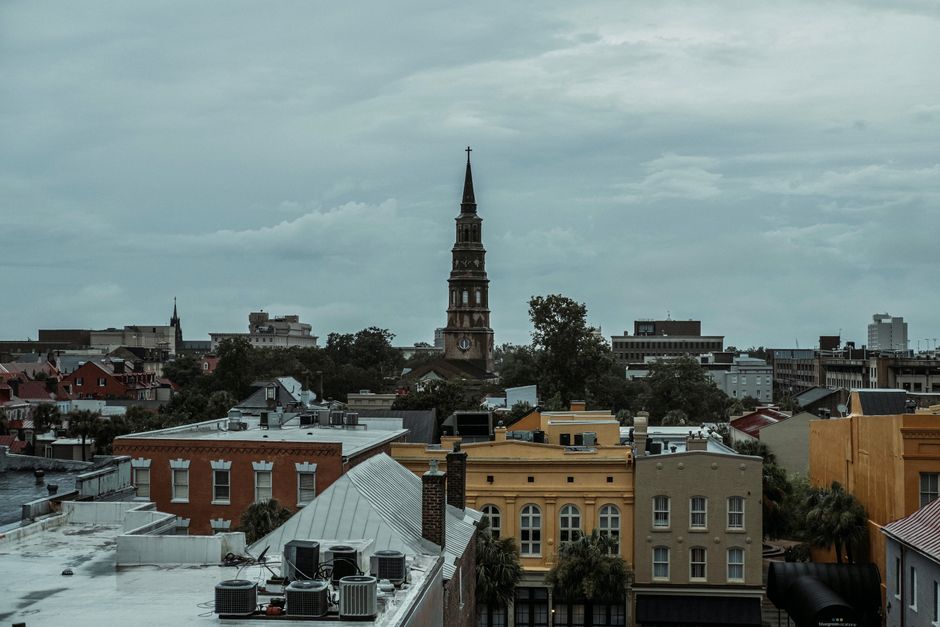
- What happened: According to the Post and Courier on October 26, 2026, unusually high king tides are flooding roads in Charleston, South Carolina, with more flooding expected.
- Who it affects: Charleston-area homeowners, homebuyers, landlords, and other property investors may face access, insurance, maintenance, and financing considerations.
- Where: The reported flooding affects Charleston, South Carolina, and other South Carolina coastal communities.
- Source: The Post and Courier, published October 26, 2026.
What is causing Charleston king tide flooding?
Charleston king tide flooding is occurring as unusually high seasonal tides flood roads in Charleston, South Carolina, and other coastal communities. According to the Post and Courier on October 26, 2026, more flooding is expected. King tides are especially high seasonal tides that can occur during otherwise ordinary weather.
Charleston, South Carolina, roads can become difficult to use when high water returns repeatedly. Repeated road flooding can interrupt access to homes, rental properties, businesses, and construction sites. It can also create additional wear for vehicles, driveways, landscaping, exterior systems, and other areas that collect water.
Charleston king tide flooding can affect property access without a named storm.
The Post and Courier report published October 26, 2026, does not establish how individual properties were affected or whether a particular home is in a flood zone. Buyers and owners should evaluate the specific property’s elevation, drainage, access routes, insurance requirements, and history of water intrusion before making a decision.
Source: Post and Courier
Why does Charleston king tide flooding matter for South Carolina property owners?
For Charleston-area property owners, recurring coastal flooding can create costs and disruptions separate from damage caused by a major storm. A flooded road may limit access to a home, rental, construction site, or commercial property. Repeated exposure can also increase maintenance needs and affect vacancy planning, tenant concerns, resale appeal, and repair decisions.
What should homeowners review?
Homeowners should review flood insurance and property insurance separately. Standard homeowners insurance may not cover flood damage, while flood coverage can have its own eligibility, limits, exclusions, and waiting periods. A qualified insurance professional can explain how coverage applies to a specific property. Owners should also document current conditions and ask local officials about drainage, road closures, and resilience projects.
What should homebuyers check before making an offer?
Flood risk can affect more than the purchase price. It may influence insurance costs, required coverage, repair planning, resale appeal, and the practical time needed to reach the property during high water. Buyers should ask for prior flood or water damage disclosures, review available flood maps, inspect drainage and elevation conditions, and confirm whether a lender requires flood insurance.
South Carolina coastal property decisions should account for recurring access and insurance issues.
What should property investors include in the analysis?
Investors should include recurring access problems, insurance premiums, repairs, vacancy risk, and tenant concerns in a property analysis. A property that looks attractive based only on rent and purchase price may produce a different return after flood-related operating costs are included. Lenders and insurers may also evaluate location and risk differently, so financing and coverage should be confirmed early.
What should Charleston property buyers watch next?
- Additional king tide flooding reported by Charleston, South Carolina, or other South Carolina coastal communities.
- Road closures, access disruptions, or recurring drainage problems near a property under consideration.
- Flood-zone information, elevation documentation, insurance requirements, and available coverage for a specific address.
- Inspection findings showing water intrusion, deferred maintenance, or improvements needed for resilience.
How can South Carolina investors and homebuyers review financing?
In South Carolina, Mortgage Bank of California dba MBANC (NMLS #38232) is licensed for both owner-occupied mortgages and investment-property lending. MBANC’s Non-QM programs may help self-employed entrepreneurs, business owners, contractors, investors, retirees, and international buyers whose income or documentation does not fit a traditional bank’s process. Review Non-QM lending in South Carolina, and discuss the property’s flood, insurance, and qualification considerations before applying.
Bottom line for South Carolina: Charleston king tide flooding makes access, insurance, maintenance, and property-specific review important parts of coastal real estate decisions. Buyers, homeowners, and investors should assess the individual property rather than assume that ordinary weather means ordinary risk.
More South Carolina coverage
- South Carolina Housing Impact: Scout Expansion Explained (October 25, 2026)
- Greer Property Tax Lawsuit: South Carolina Guide (October 24, 2026)
- South Carolina Housing Market: Westinghouse Expansion (October 21, 2026)
Go Deeper
MBANC NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
Can Charleston king tide flooding affect a mortgage decision?
Yes, Charleston king tide flooding can be a property due diligence consideration. Flood risk may affect insurance requirements, operating costs, access, inspection findings, and overall affordability for a Charleston, South Carolina, property. The lender determines qualification based on the complete application and property review, not on flooding conditions alone.
Do I need flood insurance if there is no named storm?
Flood insurance needs depend on the policy, property location, lender requirements, and coverage terms. Charleston king tide flooding can occur without a named storm, so Charleston, South Carolina, buyers and owners should ask an insurance professional how flood coverage applies to the specific property.
Can investors finance South Carolina coastal property?
Yes, investors can seek financing for South Carolina coastal property, subject to lender requirements and approval. Mortgage Bank of California dba MBANC (NMLS #38232) is licensed for investment-property lending in South Carolina. Investors should review flood exposure, insurance, access, repairs, and expected income during the financing process.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.