
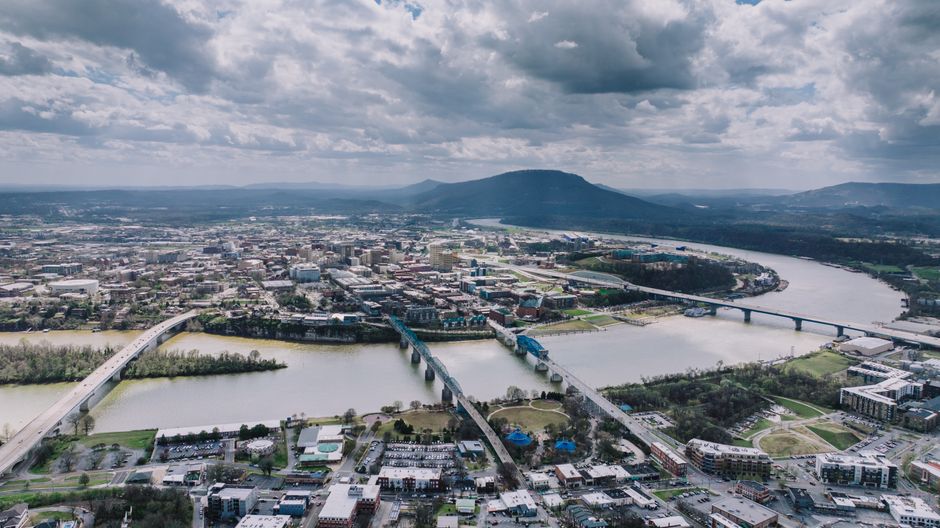
- What happened: Chattanooga ranked third in the United States for properties newly added to high-risk flood zones, according to the Chattanooga Times Free Press on September 26, 2026.
- Who it affects: Chattanooga homeowners, homebuyers, landlords, and other property investors may need to review affected properties more closely.
- Where: The reported change concerns Chattanooga, Tennessee, and properties in newly designated high-risk flood zones.
- Source: Chattanooga Times Free Press, published September 26, 2026
What happened with Chattanooga high-risk flood zones?
According to the Chattanooga Times Free Press on September 26, 2026, Chattanooga ranked third in the United States for properties newly added to high-risk flood zones. The available report summary does not state the number of properties involved, the boundaries of the affected areas, or the specific mapping process.
A high-risk flood-zone designation identifies a category of increased flood exposure; it does not by itself establish that a particular property has flooded or will flood. According to the Chattanooga Times Free Press on September 26, 2026, the new designations may affect insurance costs and availability, lender requirements, property values, and future development decisions.
Chattanooga homeowners may first want to review insurance coverage. Chattanooga homebuyers may need to consider insurance availability and documentation before closing. Chattanooga investors may need to include insurance, operating costs, tenant considerations, resale planning, and future improvements in their property review.
Source: Chattanooga Times Free Press, published September 26, 2026
Why could Chattanooga flood zones matter to Tennessee homeowners, buyers, and investors?
How can a flood-zone designation affect insurance?
According to the Chattanooga Times Free Press on September 26, 2026, new high-risk designations may affect insurance costs and availability. An insurer may reassess coverage availability, exclusions, deductibles, or premiums. Flood damage is generally treated separately from standard homeowners coverage, so owners should confirm current coverage and ask whether additional flood coverage is available. Added insurance expense can affect total housing costs.
Chattanooga flood-zone designations can change the insurance questions property owners must answer.
Can Chattanooga flood zones affect mortgage approval or closing?
According to the Chattanooga Times Free Press on September 26, 2026, new designations may affect lender requirements. Lenders commonly review flood-zone information during a property and loan process, and a borrower may need evidence of acceptable flood insurance before closing. Buyers should ask about flood-zone status early because documentation or an insurance quote may take time.
An existing designation does not automatically change the terms of an existing mortgage. However, insurance requirements can matter when a Chattanooga homeowner refinances, sells, or seeks new financing. The practical effect depends on the property’s location, the loan, the lender, and available insurance coverage.
Could a designation affect property values or development?
According to the Chattanooga Times Free Press on September 26, 2026, new high-risk designations may affect property values and future development decisions. Buyers may examine insurance costs, drainage, prior damage, access, elevation, or flood history more closely. The designation does not establish that every affected property will lose value, but it can create additional questions during inspections, negotiations, appraisals, and underwriting.
Chattanooga investors should include insurance and carrying costs in a property budget before making an offer. A designation may also affect plans for additions, renovations, replacements, or new construction. Local approvals and project requirements vary, so owners should confirm applicable rules with local authorities and qualified professionals.
Chattanooga property owners face more due-diligence questions when flood-zone maps change.
What should Chattanooga property owners watch next?
- Which Chattanooga properties and neighborhoods are included in the updated high-risk designations.
- Whether insurers change coverage availability, underwriting requirements, or pricing for affected properties.
- How lenders handle flood-zone documentation and insurance requirements for new loans and refinances.
- Whether buyers, appraisers, and developers reflect the added risk in offers, valuations, and project plans.
Financing for Tennessee homebuyers, homeowners, and investors
In Tennessee, Mortgage Bank of California dba MBANC (NMLS #38232) offers Non-QM loan programs for eligible owner-occupants, homeowners, and investment-property borrowers whose income or property situation does not fit a traditional bank’s process. Approval depends on the full application, property, credit profile, and other underwriting factors.
Bottom line for Chattanooga: New high-risk flood-zone designations may affect insurance, lending, property values, and development decisions. Chattanooga buyers, homeowners, and investors should review property-specific information early.
More Tennessee coverage
- East Tennessee Rebuilding: Property Guide for Buyers (September 25, 2026)
- East Tennessee Hurricane Helene Recovery: Housing Impact (September 24, 2026)
- Nashville Capitol Redevelopment: Tennessee Property Impact (September 23, 2026)
Go Deeper
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
Do Chattanooga high-risk flood zones mean a property has flooded?
No. A Chattanooga high-risk flood-zone designation identifies an increased flood-risk category, but it does not establish that a particular Chattanooga property has flooded or will flood. Chattanooga buyers and owners should review property-specific information and insurance options before making financing, purchase, or improvement decisions.
Can Chattanooga flood zones affect a mortgage?
Yes. Chattanooga flood zones can affect documentation and insurance requirements for a new loan or refinance. A lender may require acceptable flood insurance before closing, depending on the property and loan circumstances. Chattanooga borrowers should ask about flood-zone status and insurance requirements early in the financing process.
What should Chattanooga buyers do before making an offer?
Chattanooga buyers should ask about the property’s current flood-zone status, obtain an insurance estimate early, and include insurance and other property costs in the purchase budget. A qualified insurance professional and the lender can explain requirements for the specific Chattanooga property before the buyer makes an offer.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.