
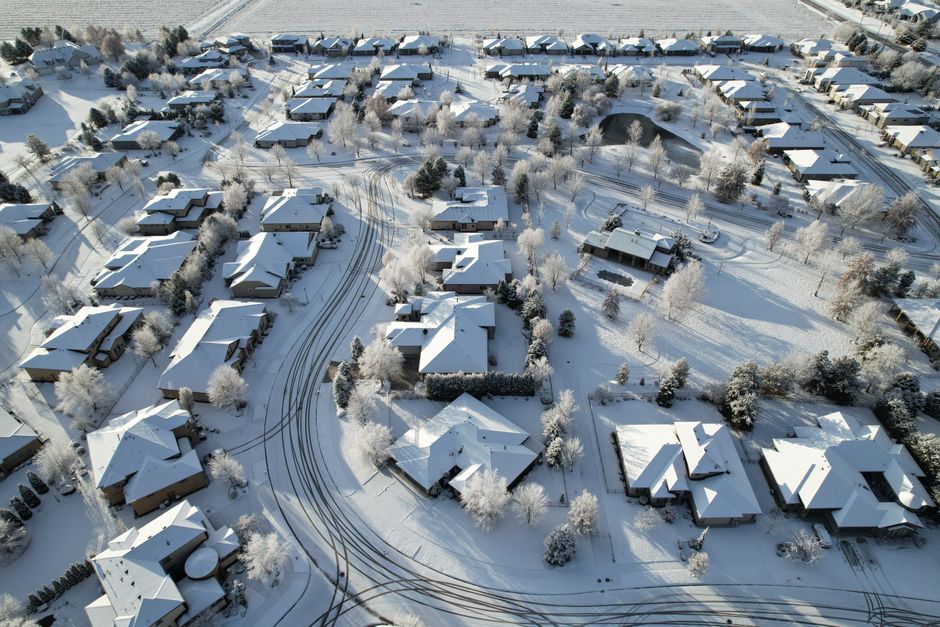
- What happened: Nearly every wildfire on Idaho state land was human-caused, according to The Cool Down on October 25, 2026.
- Reported cost: The Cool Down reported $47 million in response and damage costs on October 25, 2026.
- Who it affects: Homeowners, homebuyers and real-estate investors in wildfire-exposed Idaho areas may need to review insurance and property conditions.
- Where: The report concerns Idaho state land and nearby communities affected by wildfire risk.
- Source: The Cool Down, published October 25, 2026.
What is the Idaho wildfire mortgage impact?
According to The Cool Down on October 25, 2026, nearly every wildfire on Idaho state land was human-caused, and response and damage costs reached $47 million. The report highlights the financial burden associated with recent fire activity without providing a breakdown of the total.
Idaho wildfire mortgage impact is not a separate mortgage charge or guarantee of a lending result. It describes how wildfire exposure may affect insurance availability, property condition, property-market activity and the documentation a lender reviews before approving financing.
Idaho wildfire exposure can affect housing decisions even when a particular property has not been damaged. Insurance availability, prior damage, access, construction and defensible space can create different considerations from one property to another.
According to The Cool Down on October 25, 2026, Idaho wildfire costs reached $47 million in response and damage costs.
Source: The Cool Down
Why does wildfire risk matter for Idaho homeowners and buyers?
How can insurance affect the housing budget?
Wildfire risk may make homeowners insurance harder to obtain or more expensive in exposed areas. If insurance is required for a mortgage, a buyer may need to confirm acceptable coverage before closing. Existing homeowners can review policy limits, deductibles and renewal terms to understand whether coverage still fits the property’s risk profile.
Escrow is an account used to collect and pay certain property costs, such as insurance, as part of a mortgage payment. When insurance premiums change, escrow can affect the monthly housing budget. Buyers should request insurance quotes early because coverage questions can arise before the final stages of a transaction.
Insurance availability can shape the Idaho wildfire mortgage impact more directly than the reported public cost. According to The Cool Down on October 25, 2026, the $47 million figure combines response and damage costs, not individual homeowner insurance costs.
Could wildfire exposure affect property values or timing?
Wildfire exposure may affect how buyers evaluate a property, especially when insurance access is limited or a home has a history of damage. Idaho wildfire exposure does not mean every nearby property will lose value. Local conditions, including defensible space, construction, access, prior damage and available coverage, can produce different outcomes.
Sellers and investors may need more time to provide documentation about repairs, insurance and property condition. Investors should consider insurance availability, repair needs and potential vacancy alongside the purchase price when evaluating an Idaho property.
Idaho property values can respond differently from one neighborhood to another when wildfire exposure, insurance and property condition vary.
What documentation might lenders review?
Mortgage lenders generally evaluate whether a property is adequately insured and whether the collateral meets applicable requirements. For an Idaho property affected by wildfire risk, that review may include the insurance policy, property condition and records of completed repairs. Recent fire damage, unresolved repairs or an insurance gap can complicate financing and extend the timeline.
Homeowners considering a refinance can gather current insurance information and repair records. Buyers may want a purchase agreement and closing schedule that allow time to address insurance or property-condition questions. Requirements vary by property and lender.
What should Idaho residents watch next?
- Whether Idaho agencies report additional details about the $47 million in response and damage costs reported by The Cool Down on October 25, 2026.
- Whether insurers change availability, renewal terms or pricing in areas with elevated wildfire exposure.
- Whether Idaho property listings show longer marketing times, more disclosures or increased demand for fire-resilient homes.
- Whether lenders request additional insurance and property-condition documentation for exposed properties.
Bottom line for Idaho: Idaho wildfire risk can affect insurance, property evaluation and financing timelines, even though the $47 million reported by The Cool Down is a statewide response and damage-cost figure. Early insurance and property-condition review can help homeowners, buyers and investors identify questions sooner.
Financing for Idaho investors and borrowers when conditions change
Mortgage Bank of California dba MBANC (NMLS #38232) is licensed for owner-occupied and investment-property lending in Idaho. Its lending programs may help borrowers whose income or documentation does not fit a traditional bank’s process, including self-employed entrepreneurs, business owners, contractors, investors, retirees and international buyers. Review lending options in Idaho and discuss the property’s insurance and condition requirements early.
More Idaho coverage
- Micron Expansion Boise Real Estate: Idaho Market Outlook (October 24, 2026)
- Boise Housing Demand and Micron’s Idaho Expansion (October 21, 2026)
- Idaho Job Growth Housing Market: September Update (October 17, 2026)
Go Deeper
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
What is the Idaho wildfire mortgage impact?
The Idaho wildfire mortgage impact may include insurance, property-condition and documentation questions before financing closes. Wildfire exposure can affect whether acceptable homeowners insurance is available and whether a lender requests records about damage or repairs. Requirements vary by property and lender, so Idaho homeowners and buyers should review these issues early.
Should Idaho buyers get an insurance quote before making an offer?
Idaho buyers should request an insurance quote early because the quote can clarify coverage availability and help estimate the total housing cost before closing. Wildfire exposure, property condition and prior damage may affect the review. Early information can also identify coverage questions before the Idaho purchase process is far along.
Can investors finance an Idaho property in a wildfire-exposed area?
Investors may be able to finance an Idaho property in a wildfire-exposed area, depending on the property, insurance, borrower qualifications and loan terms. Mortgage Bank of California dba MBANC (NMLS #38232) is licensed for investment-property lending in Idaho. Insurance and property-condition questions should be discussed early.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.