
- What happened: Wisconsin Public Radio examined why homeownership remains difficult for many Wisconsin buyers.
- Who it affects: Wisconsin buyers, homeowners considering a move, self-employed borrowers, and real-estate investors.
- Where: Wisconsin.
- Source: Wisconsin Public Radio, published September 30, 2026.
What is driving Wisconsin home affordability pressure?
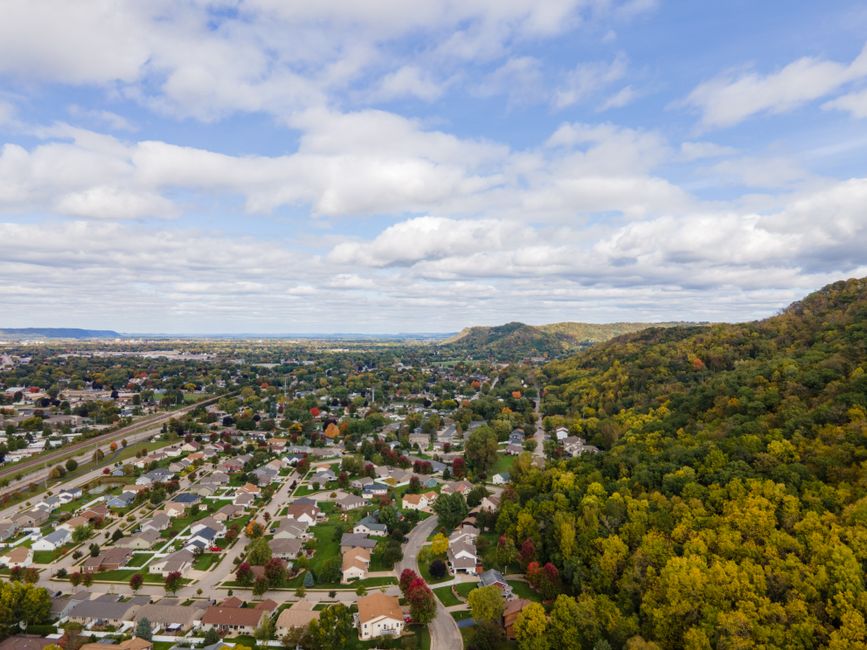
Wisconsin Public Radio examined the factors making homeownership difficult across Wisconsin, including housing costs and broader affordability pressures, according to Wisconsin Public Radio on September 30, 2026. These conditions can make it harder for prospective buyers to afford a home.
Wisconsin home affordability is not determined by the purchase price alone. Buyers also have to account for the down payment, closing costs, property taxes, homeowners insurance, maintenance, and the monthly principal and interest payment. When those costs take up more of a household’s budget, a buyer may qualify for less, need more cash upfront, or delay the purchase.
Housing costs can affect more than first-time buyers, according to Wisconsin Public Radio on September 30, 2026. Existing homeowners who want to move may have less purchasing power for a larger or better-located property. That can reduce move-up activity and limit the number of homes available to other buyers.
Wisconsin home affordability pressures can also shape real-estate investment decisions. Investors must consider whether a prospective rental property can support its operating costs and financing obligations. Higher acquisition costs or weaker affordability can affect which properties make sense, how much capital an investor needs, and how quickly a portfolio can expand.
Source: WPR
Why does Wisconsin home affordability matter to buyers and homeowners?
Why might Wisconsin buyers need to adjust their plans?
When homes are difficult to afford, buyers may consider a lower price range, a different location, a smaller property, or a longer savings period. Qualification is based on the borrower’s overall financial profile, so a buyer should review income, debts, available funds, and expected housing costs before making an offer. Self-employed borrowers may also need to organize business and personal financial records carefully.
Wisconsin buyers may need to balance purchase price, upfront cash, and ongoing housing costs. A longer preparation period or a different property target can be one response to affordability pressure. The right approach depends on each buyer’s financial circumstances and the property under consideration.
Why might Wisconsin homeowners delay moving?
If a current home no longer fits a household but the next purchase is too expensive, the owner may postpone a move or make targeted improvements instead. Reduced move-up activity can affect local inventory and may make it harder for buyers seeking a particular type of home to find one.
Wisconsin home affordability pressure can therefore influence both sides of the market. A homeowner delaying a move may reduce the number of available listings, while a buyer may have fewer opportunities to compare properties in a preferred location or price range.
How should Wisconsin investors evaluate rental properties?
For Wisconsin landlords, portfolio investors, and short-term-rental operators, affordability pressure can influence tenant demand, rent assumptions, operating expenses, and resale considerations. A rental property should be evaluated on its own income and expenses rather than on the expectation that market conditions will solve an affordability gap.
Out-of-state investors buying in Wisconsin also need to account for local management, insurance, taxes, repairs, and vacancy risk. Wisconsin rental-property economics depend on the individual property, its expected income, and its operating costs.
Wisconsin home affordability pressure can reduce purchasing power for households across the state.
What should Wisconsin buyers and investors watch next?
- Wisconsin housing costs and affordability pressures may ease or remain persistent.
- Move-up activity and available listings may change as Wisconsin homeowners reassess their plans.
- Rents, property expenses, and purchase prices may affect the economics of Wisconsin rental properties.
- Buyers and investors may increasingly seek financing that considers nontraditional income or property circumstances.
Financing for Wisconsin investors when the picture changes
Mortgage Bank of California dba MBANC (NMLS #38232) originates business-purpose loans in Wisconsin only for real-estate investors, including rental-property owners, landlords, portfolio investors, short-term-rental operators, and out-of-state investors buying in Wisconsin. MBANC’s Non-QM programs may help investors whose income, assets, or business structure does not fit a traditional bank’s standards. Explore Wisconsin investor financing options for business or investment purposes.
Bottom line for Wisconsin: Wisconsin home affordability pressures can make purchases harder for households and change which rental properties work for investors. Wisconsin investors should evaluate property income, expenses, documentation, and business-purpose financing needs separately.
More Wisconsin coverage
- Wisconsin Data Center Property Taxes: What to Watch (September 30, 2026)
- Wisconsin Housing Market: Rates and Supply Pressure Buyers (September 29, 2026)
- Wisconsin Condo Shortage: What It Means for Housing (September 28, 2026)
Go Deeper
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
Why are Wisconsin homes difficult for many buyers to afford?
Wisconsin homes are difficult for many buyers to afford because housing costs and broader affordability pressures can reduce purchasing power, according to Wisconsin Public Radio on September 30, 2026. The practical effects can include a longer savings period, a different property or location, or a delay in purchasing a home.
How can Wisconsin home affordability pressure affect current homeowners?
Wisconsin home affordability pressure can cause current homeowners to delay moving when the next property requires more purchasing power than expected. A homeowner may change the target property, remain in the current home longer, or make improvements instead. Reduced move-up activity can also affect local housing inventory.
Does MBANC offer home loans for Wisconsin primary residences?
No. In Wisconsin, Mortgage Bank of California dba MBANC (NMLS #38232) originates loans only for business or investment purposes, such as financing secured by a non-owner-occupied residential rental property. MBANC does not offer owner-occupied, primary-residence, or consumer mortgages in Wisconsin.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.