
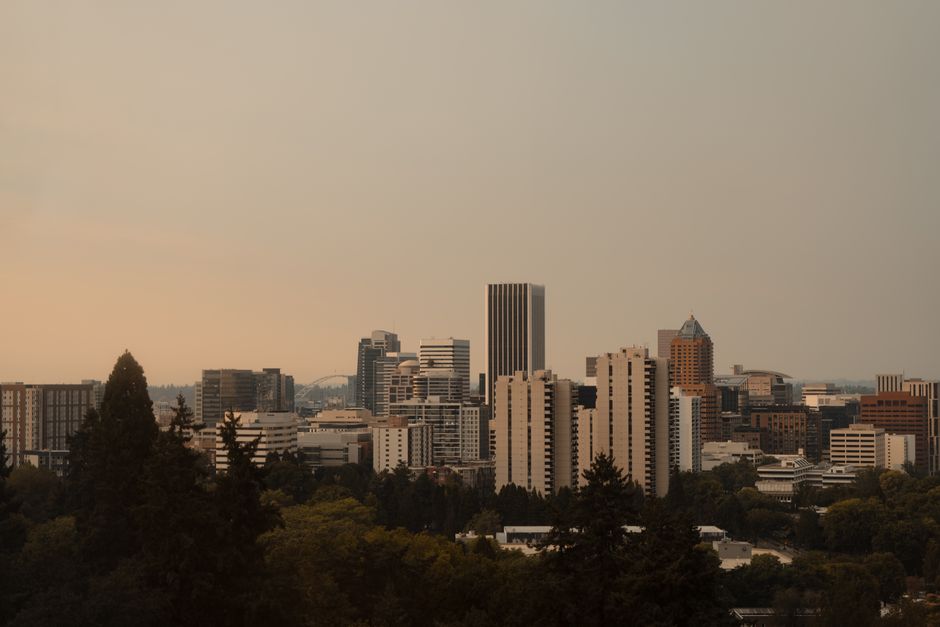
- What happened: The Portland Oregon housing market is being discussed through the lens of affordability across price ranges, according to The Wall Street Journal on September 26, 2026.
- Who it affects: Oregon homeowners, homebuyers, and real-estate investors may all need to account for uneven conditions.
- Where: The discussion focuses on Portland and the surrounding Oregon housing market.
- Source: The Wall Street Journal, published September 26, 2026.
What is happening in the Portland Oregon housing market?
According to The Wall Street Journal on September 26, 2026, the Portland Oregon housing market has become weak and uneven enough that properties across the price spectrum are increasingly discussed through the lens of affordability. The report describes broader real-estate difficulties across the region rather than identifying one isolated segment as the source of the problem.
Portland’s affordability conversation is therefore not limited to entry-level homes. According to The Wall Street Journal on September 26, 2026, affordability has become relevant across a wide range of Portland properties as buyers and sellers respond to broader market conditions.
The Wall Street Journal report, published September 26, 2026, does not provide specific sales figures, price changes, inventory levels, or marketing times. Those details would be needed to measure how conditions differ among neighborhoods, property types, and price points.
Portland’s housing market is being evaluated across the full price spectrum, not only among entry-level homes.
Source: The Wall Street Journal, published September 26, 2026.
Why does the Portland Oregon housing market matter to homeowners, buyers, and investors?
Could Portland buyers have more negotiating room?
A softer and uneven market can give Portland buyers more opportunity to compare homes, request repairs, negotiate price, or ask for additional time during due diligence. Due diligence is the period when a buyer investigates a property before completing the purchase. According to The Wall Street Journal on September 26, 2026, broader weakness may affect properties across price ranges, but negotiating leverage will still vary by neighborhood, condition, seller motivation, and competition.
Affordability is more than the purchase price. Buyers should evaluate principal, interest, property taxes, insurance, and association dues, along with property condition and maintenance needs. A lower price can improve the initial calculation, but other ownership costs and financing terms can still affect whether a home fits a buyer’s budget.
Portland buyers may have more negotiating room, but property-specific conditions still determine leverage.
What could Portland homeowners face when selling?
Portland homeowners preparing to sell may face longer marketing times and pressure on perceived property values when buyers have more choices or negotiate more aggressively. A realistic list price, thorough preparation, and clear documentation of improvements can help present a home effectively. The Wall Street Journal report published September 26, 2026, does not establish how long homes are taking to sell or how values have changed, so local property-specific analysis remains important.
What should Oregon investors examine?
For Oregon investors, a softer market can create opportunities to negotiate on acquisition price or terms. According to The Wall Street Journal on September 26, 2026, the broader market is weak and uneven, which makes conservative assumptions especially important. Investors should examine expected rent, vacancy, repairs, insurance, taxes, financing costs, and the property’s likely resale market. A property that appears inexpensive may still produce weak returns if operating costs or needed improvements are higher than expected.
Why does qualification still matter?
More accessible prices do not automatically make financing easier. Lenders may still review income history, credit, assets, property type, occupancy, debt obligations, and the consistency of a borrower’s financial profile. Self-employed borrowers, contractors, business owners, retirees, and investors may need to document finances differently from a traditional salaried applicant. The Wall Street Journal report published September 26, 2026, does not change those individual underwriting considerations.
What should Oregon buyers and sellers watch next?
- Whether Portland sales activity and listing times improve or weaken further.
- Whether affordability concerns remain broad or become concentrated in specific neighborhoods and price ranges.
- How asking prices compare with completed sales and accepted offers.
- Whether lenders and appraisers continue to apply close scrutiny to borrowers and properties.
According to The Wall Street Journal on September 26, 2026, the Portland market’s challenge is broader than one property segment. Buyers, sellers, and investors should compare each property’s condition, location, costs, and likely alternatives rather than assume that one market description applies equally everywhere.
Portland’s broader housing-market weakness may create opportunities, but affordability and financing remain property- and borrower-specific.
Bottom line for Oregon: The Portland Oregon housing market is soft and uneven across price ranges, according to The Wall Street Journal on September 26, 2026. Buyers and investors may find negotiating opportunities, while homeowners should prepare for a more deliberate sale strategy.
More Oregon coverage
- Oregon Wildfires Housing Impact: What to Know (September 25, 2026)
- Oregon Housing Aid: What $7.45 Million Means for Residents (September 24, 2026)
- Oregon Affordable Housing Funding: What It Means (September 23, 2026)
Go Deeper
How can Oregon investors explore financing when the market changes?
Mortgage Bank of California dba MBANC (NMLS #38232) offers Non-QM financing for Oregon investors and may also work with borrowers whose finances do not fit a traditional bank’s standard model, including self-employed entrepreneurs, business owners, contractors, retirees, and international buyers. Review Non-QM lending in Oregon and discuss individual qualifications before making an offer.
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
What does the Portland Oregon housing market outlook mean for affordability?
The Portland Oregon housing market is increasingly being discussed through the lens of affordability across price ranges, according to The Wall Street Journal on September 26, 2026. The report does not say that every Portland property is affordable for every buyer, and it does not provide specific prices, sales figures, or neighborhood-level measurements.
Could Portland buyers have more negotiating power?
Portland buyers could have more negotiating power if a softer market gives buyers additional choices or reduces competition. The Wall Street Journal reported on September 26, 2026, that Portland conditions are weak and uneven, but negotiating leverage still depends on the property, neighborhood, seller, condition, and competing offers.
Can a lower Portland home price make financing automatic?
No. A lower Portland home price does not make financing automatic because lenders still review the borrower’s finances and the property. Self-employed borrowers and other nontraditional borrowers may need to satisfy underwriting requirements even when a home appears more accessible, and approval remains subject to individual qualifications.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.