
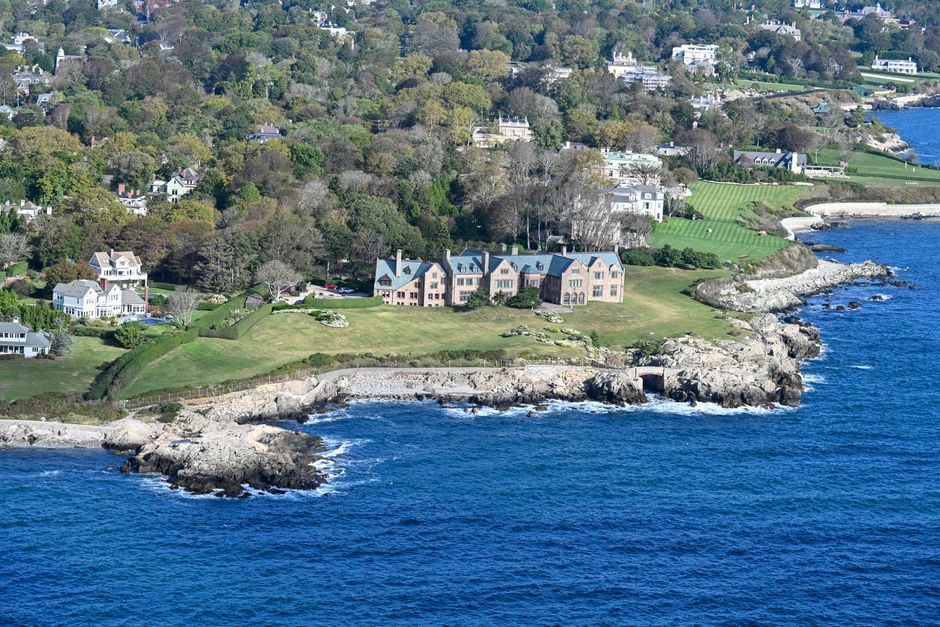
- What happened: According to The Providence Journal on September 22, 2026, a powerful nor’easter could bring prolonged coastal wind, heavy surf, and flooding threats.
- Who it affects: Rhode Island coastal and low-lying property owners, buyers, landlords, and investors could face property and access concerns.
- Where: Rhode Island coastal communities and transportation routes could experience storm-related disruptions.
- Source: The Providence Journal, published September 22, 2026.
What happened with the Rhode Island nor’easter?
According to The Providence Journal on September 22, 2026, a powerful nor’easter is expected to affect Rhode Island with prolonged coastal wind, heavy surf, and flooding threats. The Providence Journal reported that coastal communities and transportation could be affected over several days.
Rhode Island nor’easter property risks may be greater for buildings near the water or in low-lying areas. Potential concerns include water intrusion, wind-related damage, power outages, and difficulty reaching a property. The specific effect on a property will depend on its location and the storm’s severity.
Rhode Island coastal properties may face several days of storm-related access and operating challenges.
An appraisal district is a local agency that determines property values for taxation. In a coastal property review, investors can also examine elevation, drainage, flood maps, prior claims, roof and exterior condition, utility vulnerability, and access routes. These details can influence maintenance planning, insurance discussions, tenant communication, and repair timing.
Source: The Providence Journal
Why do Rhode Island nor’easter property risks matter to owners and investors?
How can insurance and property costs change?
Homeowners and landlords in coastal or low-lying areas should review whether their policies address wind, flooding, water intrusion, temporary relocation, and loss of rental income. These coverages may differ. Property owners should ask an insurance professional about exclusions, deductibles, documentation, and required mitigation measures.
For buyers and investors, insurance availability and cost can affect the total expense of owning a Rhode Island property. A purchase price or projected rental income does not show the full risk by itself. Recurring premiums, deductibles, repairs, and reserves can change an investment’s expected return, so investors should seek insurance information early.
Rhode Island investment properties need storm planning that covers both physical damage and interrupted operations.
How could access and tenants affect operations?
According to The Providence Journal on September 22, 2026, transportation could be affected over several days. For landlords and short-term-rental operators, access disruptions may delay inspections, repairs, cleaning, maintenance, and tenant support. Investors should plan for occupant communication, safe property checks, protection of vulnerable equipment, and condition documentation before and after the storm.
For a property under contract, weather-related disruption may complicate inspections, appraisals, title work, settlement logistics, or final walkthroughs. Buyers should coordinate with real-estate and lending professionals about timing or property-condition changes. Investors evaluating a rental should also consider whether a temporary interruption could affect projected income.
What should investors examine over the longer term?
A single storm does not establish the long-term risk of every Rhode Island property. However, investors can use the event to examine elevation, drainage, flood maps, prior claims, roof and exterior condition, utility vulnerability, and access routes. These factors may affect maintenance needs, financing documentation, insurance, tenant demand, and resale considerations.
What should Rhode Island property owners watch next?
- Updated forecasts describing the storm’s track, duration, wind, surf, and flooding risk.
- Local advisories about coastal flooding, road closures, outages, and transportation access.
- Insurer, municipal, or emergency guidance affecting property protection and claims documentation.
- Post-storm inspections showing whether specific properties sustained damage or experienced extended access problems.
Bottom line for Rhode Island: Rhode Island nor’easter property risks may affect insurance, access, repairs, and rental operations. Investors should assess storm exposure and operating reserves before making a property decision.
More Rhode Island coverage
- Rhode Island Housing Affordability and Household Costs (September 18, 2026)
- Rhode Island Housing Market: What Coventry’s 360 Units Mean (September 17, 2026)
- Rhode Island Winter Power Rate: What Homeowners Should Know (September 16, 2026)
Go Deeper
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
What are Rhode Island nor’easter property risks?
Rhode Island nor’easter property risks include possible flooding, wind damage, heavy surf, power outages, access disruptions, and interrupted rental operations. The Providence Journal reported on September 22, 2026, that a powerful nor’easter could affect Rhode Island coastal communities and transportation over several days. Conditions and damage will vary by property location and storm severity.
What should Rhode Island investors review before buying a rental property?
Rhode Island investors should review flood and storm exposure, insurance terms, drainage, elevation, prior damage, access routes, maintenance needs, and reserves for repairs or interrupted income. Investors should also confirm whether projected rental income remains reasonable if access or operations are temporarily disrupted. Insurance and property information should be obtained early.
Can Mbanc finance an owner-occupied home in Rhode Island?
No. Mortgage Bank of California dba MBANC (NMLS #38232) originates loans in Rhode Island only for business or investment purposes, including eligible non-owner-occupied residential rental property. Mbanc does not offer owner-occupied, primary-residence, or consumer mortgages in Rhode Island. Rhode Island investors can review the company’s investment lending options.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.