
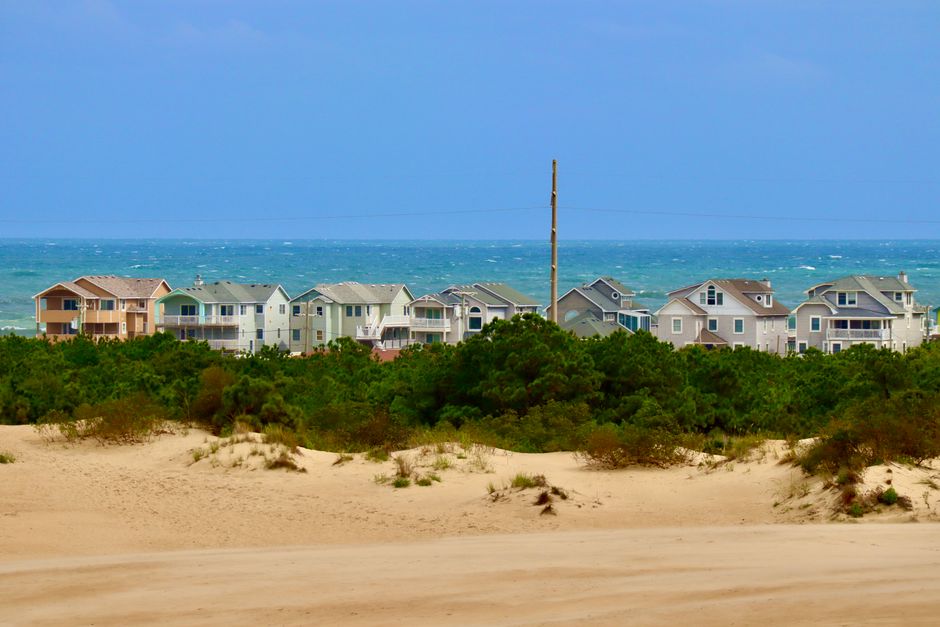
- What happened: A nor’easter brought continued coastal flooding, leaving sections of NC 12 underwater and extending the flood warning.
- Who it affects: Outer Banks homeowners, homebuyers, property owners, businesses, and real-estate investors.
- Where: The Outer Banks and nearby areas served by NC 12 in North Carolina.
- Source: CBS17.com, published September 25, 2026
What happened
According to CBS17.com, a nor’easter continued to bring coastal flooding to the Outer Banks for a second day. Sections of NC 12 were underwater, and the coastal flood warning was extended.
NC 12 is a key route through parts of the Outer Banks. When flooding affects a primary road, residents, workers, guests, contractors, emergency services, and prospective buyers may have difficulty reaching homes and businesses. The immediate effect can vary by location, elevation, road conditions, and the duration of the warning.
For property owners, a coastal flooding event can create concerns about water intrusion, erosion, cleanup, electrical systems, heating and cooling equipment, and other repairs. The summary from CBS17.com does not provide property damage totals or details about individual homes, so owners should confirm conditions directly and rely on official local guidance before entering an affected property.
Source: CBS17.com
Why it matters for North Carolina homeowners, buyers, and investors
Access can affect property operations
Flooded roads can delay inspections, maintenance, deliveries, contractor visits, tenant support, and showings. For an owner-occupied home, that may mean difficulty returning to or maintaining the property. For a rental or vacation property, access problems can interrupt normal operations and delay repairs. Investors evaluating an Outer Banks property may need to account for access conditions when setting inspection and closing timelines.
Damage and insurance questions may become more important
Coastal property owners should document visible conditions, follow instructions from local authorities, and contact their insurance provider when appropriate. Flood damage and other forms of water-related damage may be treated differently under an insurance policy, so coverage depends on the policy terms and the cause of loss. Buyers should review insurance availability, required coverage, deductibles, and exclusions early in the transaction.
Financing and valuation may require careful timing
Flooding does not automatically determine a property’s value or financing outcome. However, an event can affect the practical timing of an appraisal, inspection, repairs, documentation, and final walk-through. If a property has damage or access remains limited, the lender and other transaction participants may need current information before a loan can close. Investors should also consider repair costs, operating interruptions, and whether the property can support its planned use after conditions improve.
Homeowners considering a refinance or buyers preparing an offer should avoid assuming that a recent event will have no effect on the process. Ask the relevant professionals what documentation is needed, whether repairs must be completed, and how insurance requirements apply to the specific property.
What to watch next
- Whether the coastal flood warning is lifted or extended again.
- Whether additional sections of NC 12 become difficult or unsafe to use.
- Official updates about road access, closures, and conditions near specific properties.
- Insurance, inspection, and repair requirements for properties affected by water or access disruptions.
Financing when the picture changes
Mbanc’s Non-QM programs may help North Carolina owner-occupants and real-estate investors whose income or documentation does not fit a traditional bank’s guidelines, including self-employed entrepreneurs, business owners, contractors, retirees, and other qualified borrowers. Explore Non-QM lending in North Carolina to understand available financing options as property conditions and timing become clearer.
More North Carolina coverage
- Western North Carolina Recovery Plan and Housing Effects (September 25, 2026)
- Western North Carolina Helene Recovery Plan and Housing (September 24, 2026)
- North Carolina Coastal Flooding: Wilmington to Outer Banks (September 23, 2026)
Go Deeper
Mbanc NMLS #38232 | Equal Housing Opportunity Lender
Frequently Asked Questions
How can flooding affect an Outer Banks home purchase?
Flooding can affect access, inspections, appraisals, repairs, insurance review, and closing timing. The effect depends on the property and current conditions. Confirm requirements with the lender, insurer, inspector, and other transaction professionals.
Should Outer Banks property owners contact their insurer after flooding?
Owners should review their policy and contact their insurance provider when appropriate. Coverage depends on the policy terms and the cause of damage. They should also follow local safety guidance and document conditions when it is safe to do so.
Can investors still seek financing for a North Carolina coastal property?
Investors may still seek financing, but the property condition, access, insurance, documentation, and intended use can affect the review. Mbanc is licensed in North Carolina for investment-property lending, subject to credit approval and program requirements.
Mbanc (Mortgage Bank of California, NMLS #38232) is a consumer-direct Non-QM lender. This content is for informational purposes only and does not constitute a commitment to lend. All loans subject to credit approval.